CPA for Restaurants & Bars
The FICA tip credit most operators never claim, food cost that's measured instead of guessed, Texas mixed beverage taxes handled correctly, and a build-out broken into components instead of buried in one 39-year asset.
Three Points of Food Cost Is the Whole Profit Margin
Restaurants operate on margins thin enough that an accounting error is indistinguishable from an operating problem. If food cost is calculated from purchases instead of from inventory movement, the number swings with delivery schedules and tells you nothing. If the mixed beverage gross receipts tax is sitting in revenue instead of being handled properly, your beverage margin is wrong every single month. Owners end up managing by bank balance, which is the most expensive way to run a restaurant.
Then there's the tip credit. Section 45B gives food and beverage employers a dollar-for-dollar income tax credit for employer FICA paid on tips, and in our experience a striking share of independent operators have never claimed it — often because their preparer treated the restaurant like any other small business. On a place with meaningful tipped sales it's frequently thousands of dollars a year, and prior years can often be recovered by amending.
We set up the chart of accounts the way the industry actually reports — prime cost, food and beverage split, labor by category — so the monthly statements answer operating questions instead of just satisfying the tax return.
- FICA tip credit (Section 45B) calculation and recovery
- Tip reporting, allocation, and Form 8027
- Food and beverage cost with real inventory accounting
- Prime cost reporting and labor analysis
- Texas sales tax and mixed beverage taxes
- Build-out cost segregation and depreciation
- Smallwares, uniforms, and supplies treatment
- Payroll setup for tipped employees
Accounting That Matches How a Restaurant Runs
The FICA Tip Credit
We calculate the Section 45B credit properly, claim it on the current return, and review prior years to see whether amending is worth it. For most tipped operations this single item more than covers our fee.
Tip Compliance
Reported tips, allocated tips, Form 8027 filing for large establishments, tip pooling arrangements, and payroll configured so the tip credit against minimum wage is applied correctly on every check.
Inventory & Food Cost
Beginning inventory, purchases, ending inventory — a real cost of goods sold, not a purchases proxy. Once that's in place, food cost percentage becomes a number you can actually manage waste and theft against.
Mixed Beverage Taxes
Texas mixed beverage gross receipts tax and mixed beverage sales tax are separate obligations with different treatment. We get them off your revenue line and onto the right accounts so beverage margin means something.
Build-Out & Equipment
A construction invoice broken into components — equipment, qualified improvement property, structural — so Section 179 and bonus depreciation apply where they can, instead of capitalizing the whole project over 39 years.
Prime Cost Reporting
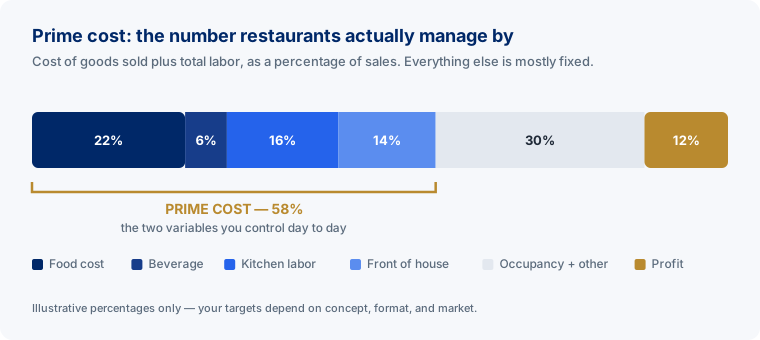
Monthly statements built on the metric operators actually run by: cost of goods plus total labor as a percentage of sales, with food and beverage separated and labor broken into kitchen, front of house, and management.
Where Restaurant Money Quietly Goes
Every item below is something we've found on an incoming client's prior-year return or books. None of them are exotic. They're what happens when a restaurant is prepared by someone whose other ninety clients aren't restaurants.
- FICA tip credit never claimed — often for several open years
- Entire build-out capitalized as one long-lived asset
- Mixed beverage gross receipts tax buried in sales revenue
- Smallwares capitalized instead of treated as materials and supplies
- No physical inventory, so food cost is a purchases proxy
- Tip credit against minimum wage misconfigured in payroll
- Owner draws run through payroll, or wages run through draws
What Good Looks Like
A restaurant with clean books closes the month within ten days, knows food cost and prime cost to the tenth of a point, can tell you beverage margin separately from food, and never guesses at the sales tax remittance. When a landlord, franchisor, or SBA lender asks for financial statements, they already exist and a CPA can compile or review them without a three-week cleanup first.
That's not a bigger accounting budget. It's the same work, organized around the business instead of around the tax return.
Restaurant Accounting Questions
What is the FICA tip credit and am I missing it?
It's the credit for employer social security and Medicare taxes paid on employee tips, under Section 45B. Food and beverage employers get a dollar-for-dollar income tax credit for the employer FICA paid on tips above the amount treated as wages for minimum wage purposes. It's one of the most frequently missed credits in the industry, and unclaimed prior years can often be recovered by amending within the statute of limitations. We check it on every new restaurant client, and we find it unclaimed more often than not.
Do I have to file Form 8027?
Form 8027 is required annually from large food and beverage establishments — generally those where tipping is customary and more than ten employees worked on a typical business day during the preceding year. If reported tips fall below a threshold percentage of gross receipts, tip allocation may be required. Plenty of operators cross the employee count during a good year without realizing a new filing obligation started with it.
How are Texas mixed beverage taxes handled?
Texas imposes a mixed beverage gross receipts tax on the permittee and a mixed beverage sales tax collected from the customer. They're separate taxes with separate treatment, and how you price and record them affects both reported revenue and tax liability. Leaving the gross receipts tax inside sales revenue is a common bookkeeping error that inflates your top line and distorts every beverage margin calculation downstream.
How should I be tracking food cost?
Not by looking at what you spent on food this month. True food cost is beginning inventory plus purchases minus ending inventory, measured against sales for the same period. Without a periodic physical count, purchases stand in for cost of goods sold and the percentage moves with delivery timing rather than actual usage — which conveniently hides both waste and theft. A weekly or monthly count is tedious and it's the difference between managing the kitchen and hoping.
Can I deduct my restaurant build-out all at once?
Parts of it, often. Build-outs mix components with very different recovery periods: equipment, qualified improvement property, and structural work each have their own treatment, and Section 179 and bonus depreciation may apply to some of it. The savings come from breaking the contractor's invoice into components rather than capitalizing the whole project as one 39-year asset — which is exactly what happens when nobody asks for the cost breakdown before the return is filed.
Should my restaurant be an S-corp?
It depends on profit, not revenue — and restaurants can have large revenue with thin profit, which is where a poorly reasoned S-corp election creates payroll costs without producing savings. There's also a real interaction with the tip credit and with owner compensation that a generic S-corp analysis misses. Run your numbers through the S-corp calculator for a rough answer, then let's look at your actual P&L.
From Our Blog
The Tip Credit Most Operators Never Claim
What Section 45B is worth, why it gets missed, and how to check whether prior years can be recovered by amending.
Read the article →Your Food Cost Percentage Is Probably Wrong
Inventory-based cost of goods sold, separating food from beverage, the mixed beverage tax trap, and why prime cost is the real metric.
Read the article →Let Us Check Your Tip Credit
Send your last business return and a recent payroll summary. If the FICA tip credit was missed, we'll tell you how much and whether prior years are recoverable — usually within a couple of days.
Related: Salons & barbershops · Construction contractors